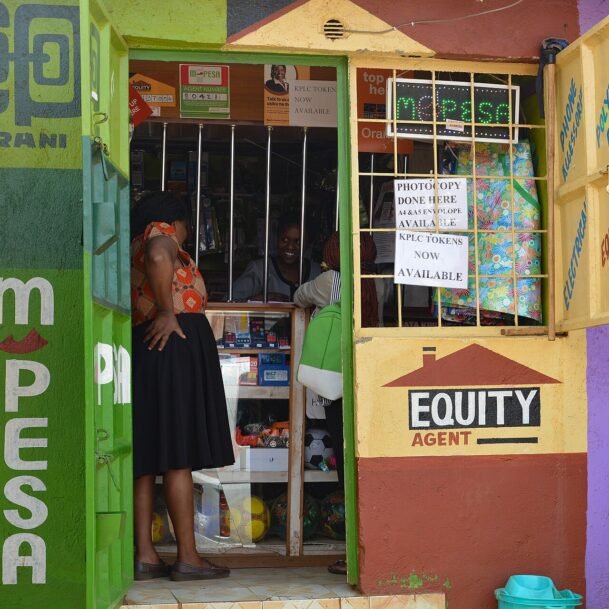
Remittance fees take more from families than most people notice. Africa received an estimated $124.2 billion in remittances in 2025, according to the International Fund for Agricultural Development (IFAD), a United Nations agency. Sending $200 to Africa through a non-bank provider cost 7.2% in late 2025. The United Nations wants that figure under 3%. Close the gap, and families keep about $5.2 billion a year. That number is our own arithmetic, and it comes with a catch we explain below.
How we get to $5.2 billion in remittance fees
Here is the math, so you can check it yourself. IFAD’s Sending Money Home 2026 report puts remittances to Africa at $124.2 billion in 2025, up 86% in a decade. Capital Ethiopia, reporting on the same IFAD data, gives the late-2025 non-bank cost of sending $200 to Africa as 7.2%. That was down from 9.0% in 2016.
The United Nations Sustainable Development Goals set a target of less than 3% by 2030 for migrant remittance costs. They also ask countries to end routes where fees exceed 5%. The gap between 7.2% and 3% is 4.2 percentage points. Multiply 4.2% by $124.2 billion, and you get about $5.2 billion.
That is slightly more than the $5.0 billion Kenya received in all of 2025. Put another way, the fee gap exceeds the whole inflow of one of Africa’s top five recipients.
| Country | 2025 inflow | Fee gap at 4.2 points |
|---|---|---|
| Egypt | $41.5 billion | about $1.74 billion |
| Nigeria | $22.8 billion | about $0.96 billion |
| Ethiopia | $7.1 billion | about $0.30 billion |
| Kenya | $5.0 billion | about $0.21 billion |
The last column applies one 4.2-point gap to every country. Treat it as a rough guide, because each corridor has its own price.
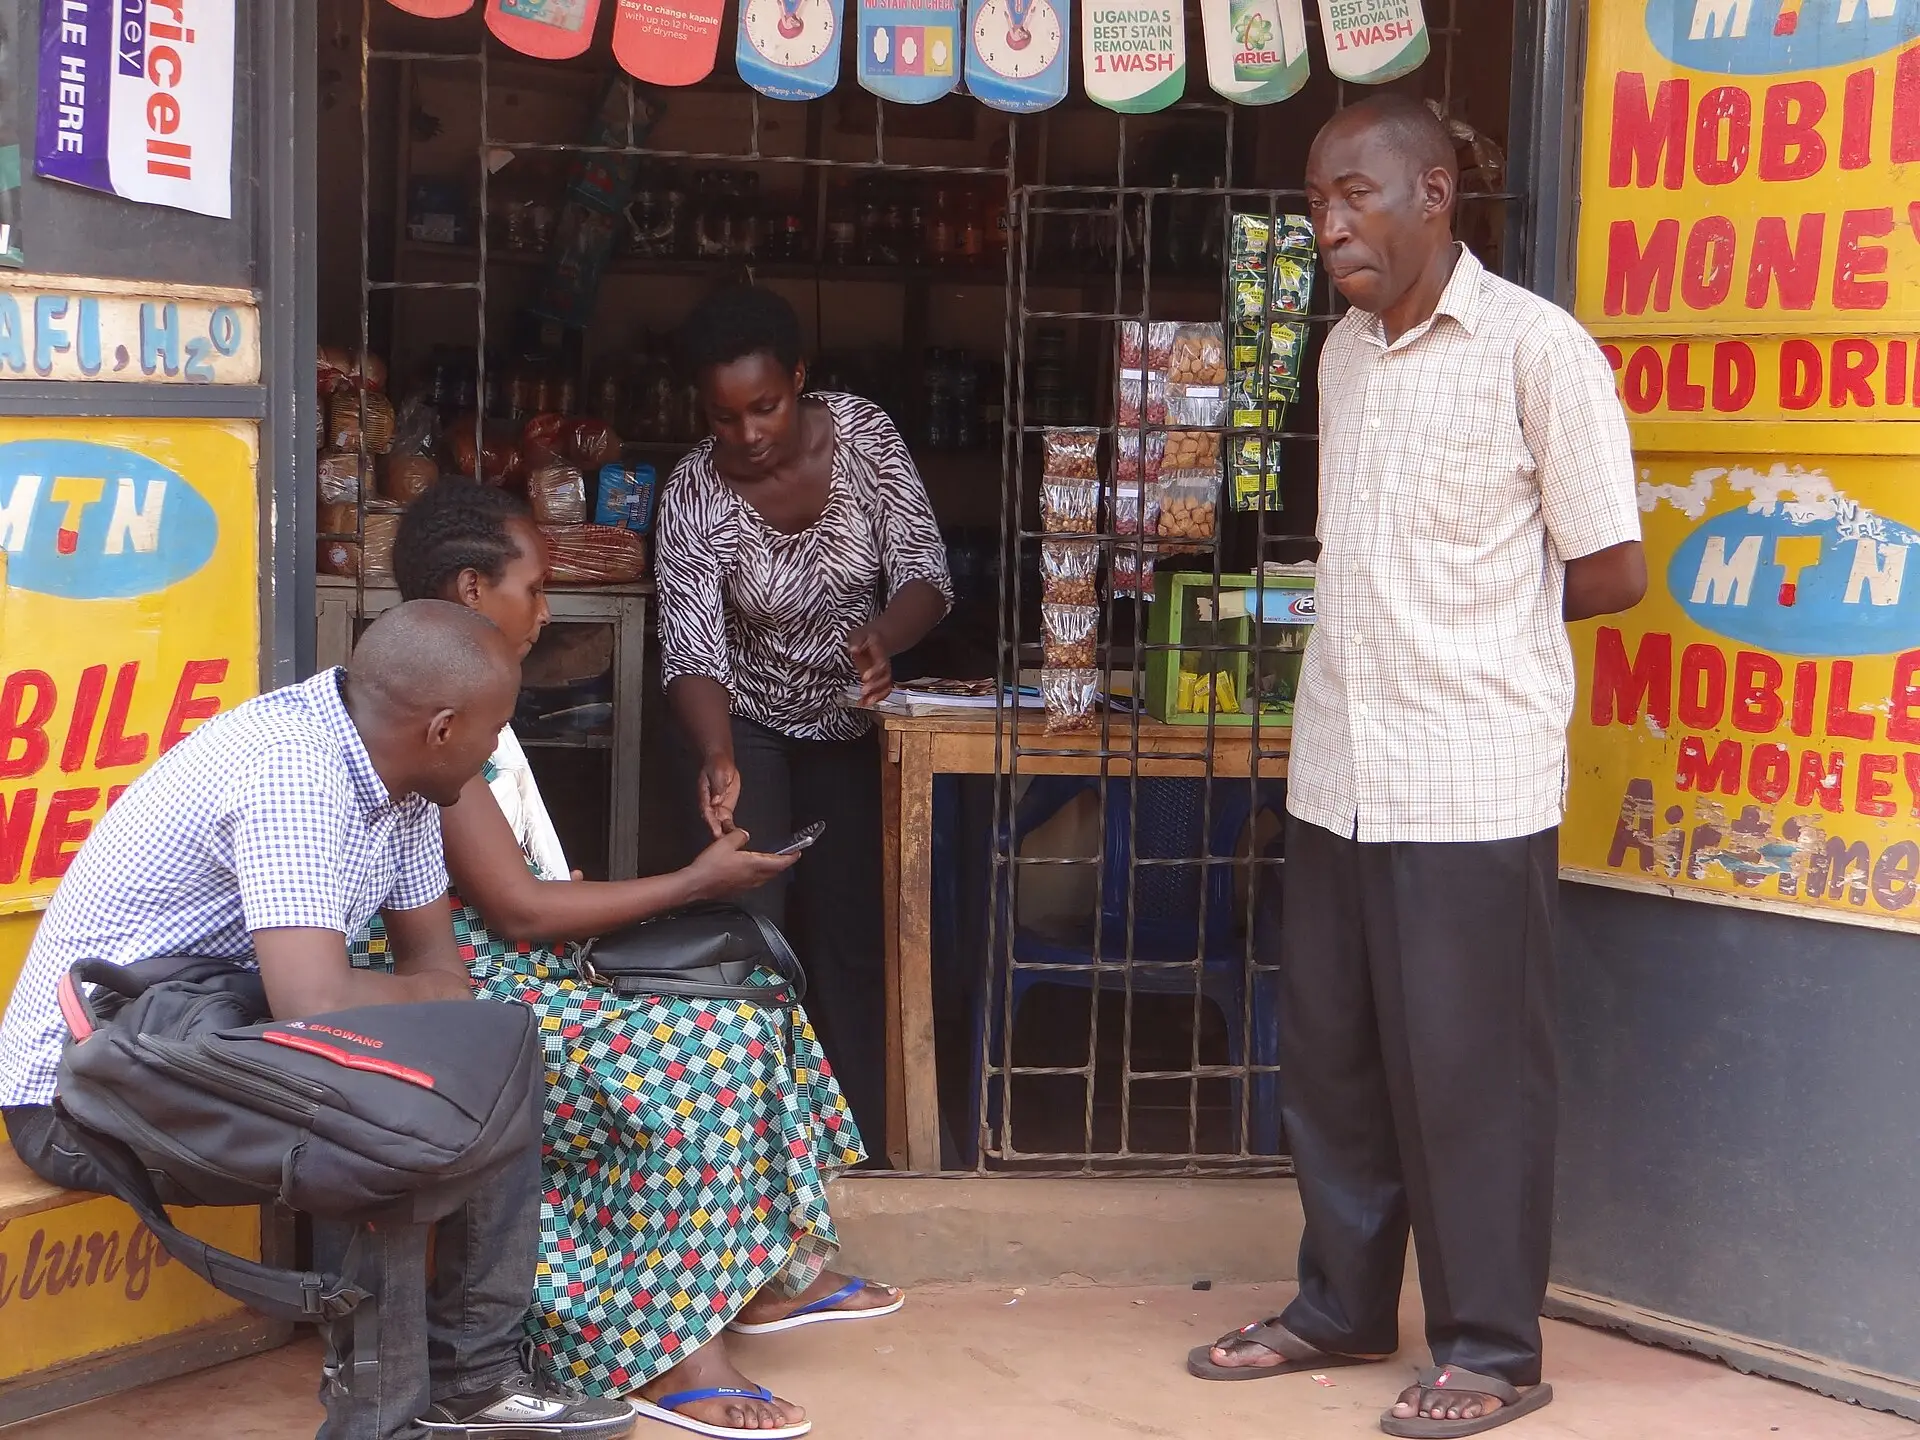
Why $5.2 billion is a ceiling
Now the catch. The 7.2% figure measures the price of a $200 send through non-bank providers. It does not weight that price by how much money moves on each route. Also, Inter Press Service (IPS) reports that the average remittance has grown from about $200 a decade ago to between $400 and $450. Fees can change with the amount sent, so the cost on larger transfers may differ from the $200 benchmark.
A second figure points the same way. The IPS coverage of the report puts the average fee at 6.4%, more than double the 3% target. The averages differ, but the direction matches. Even if remittance fees fell only halfway to the target, families would keep about $2.6 billion.
So treat $5.2 billion as an illustrative ceiling. It sizes the problem. It predicts nothing.
The ceiling still matters, because remittance fees land on the most personal money there is: a parent, a sibling or a spouse sending support. Take a $200 send. If it loses 7.2% to fees, $185.60 arrives. At 3%, $194 arrives. The $8.40 gap looks small once. Repeated monthly across millions of households, it adds up to the billions above.
Lower remittance fees already exist
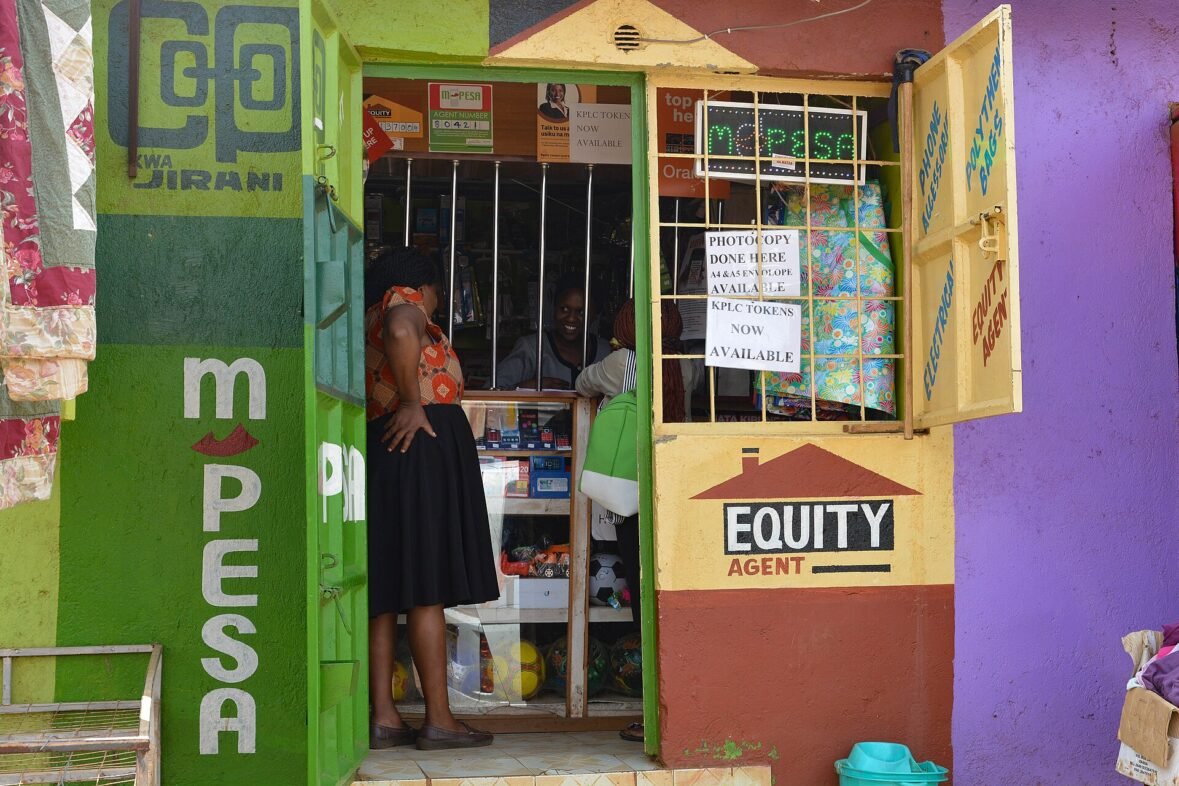
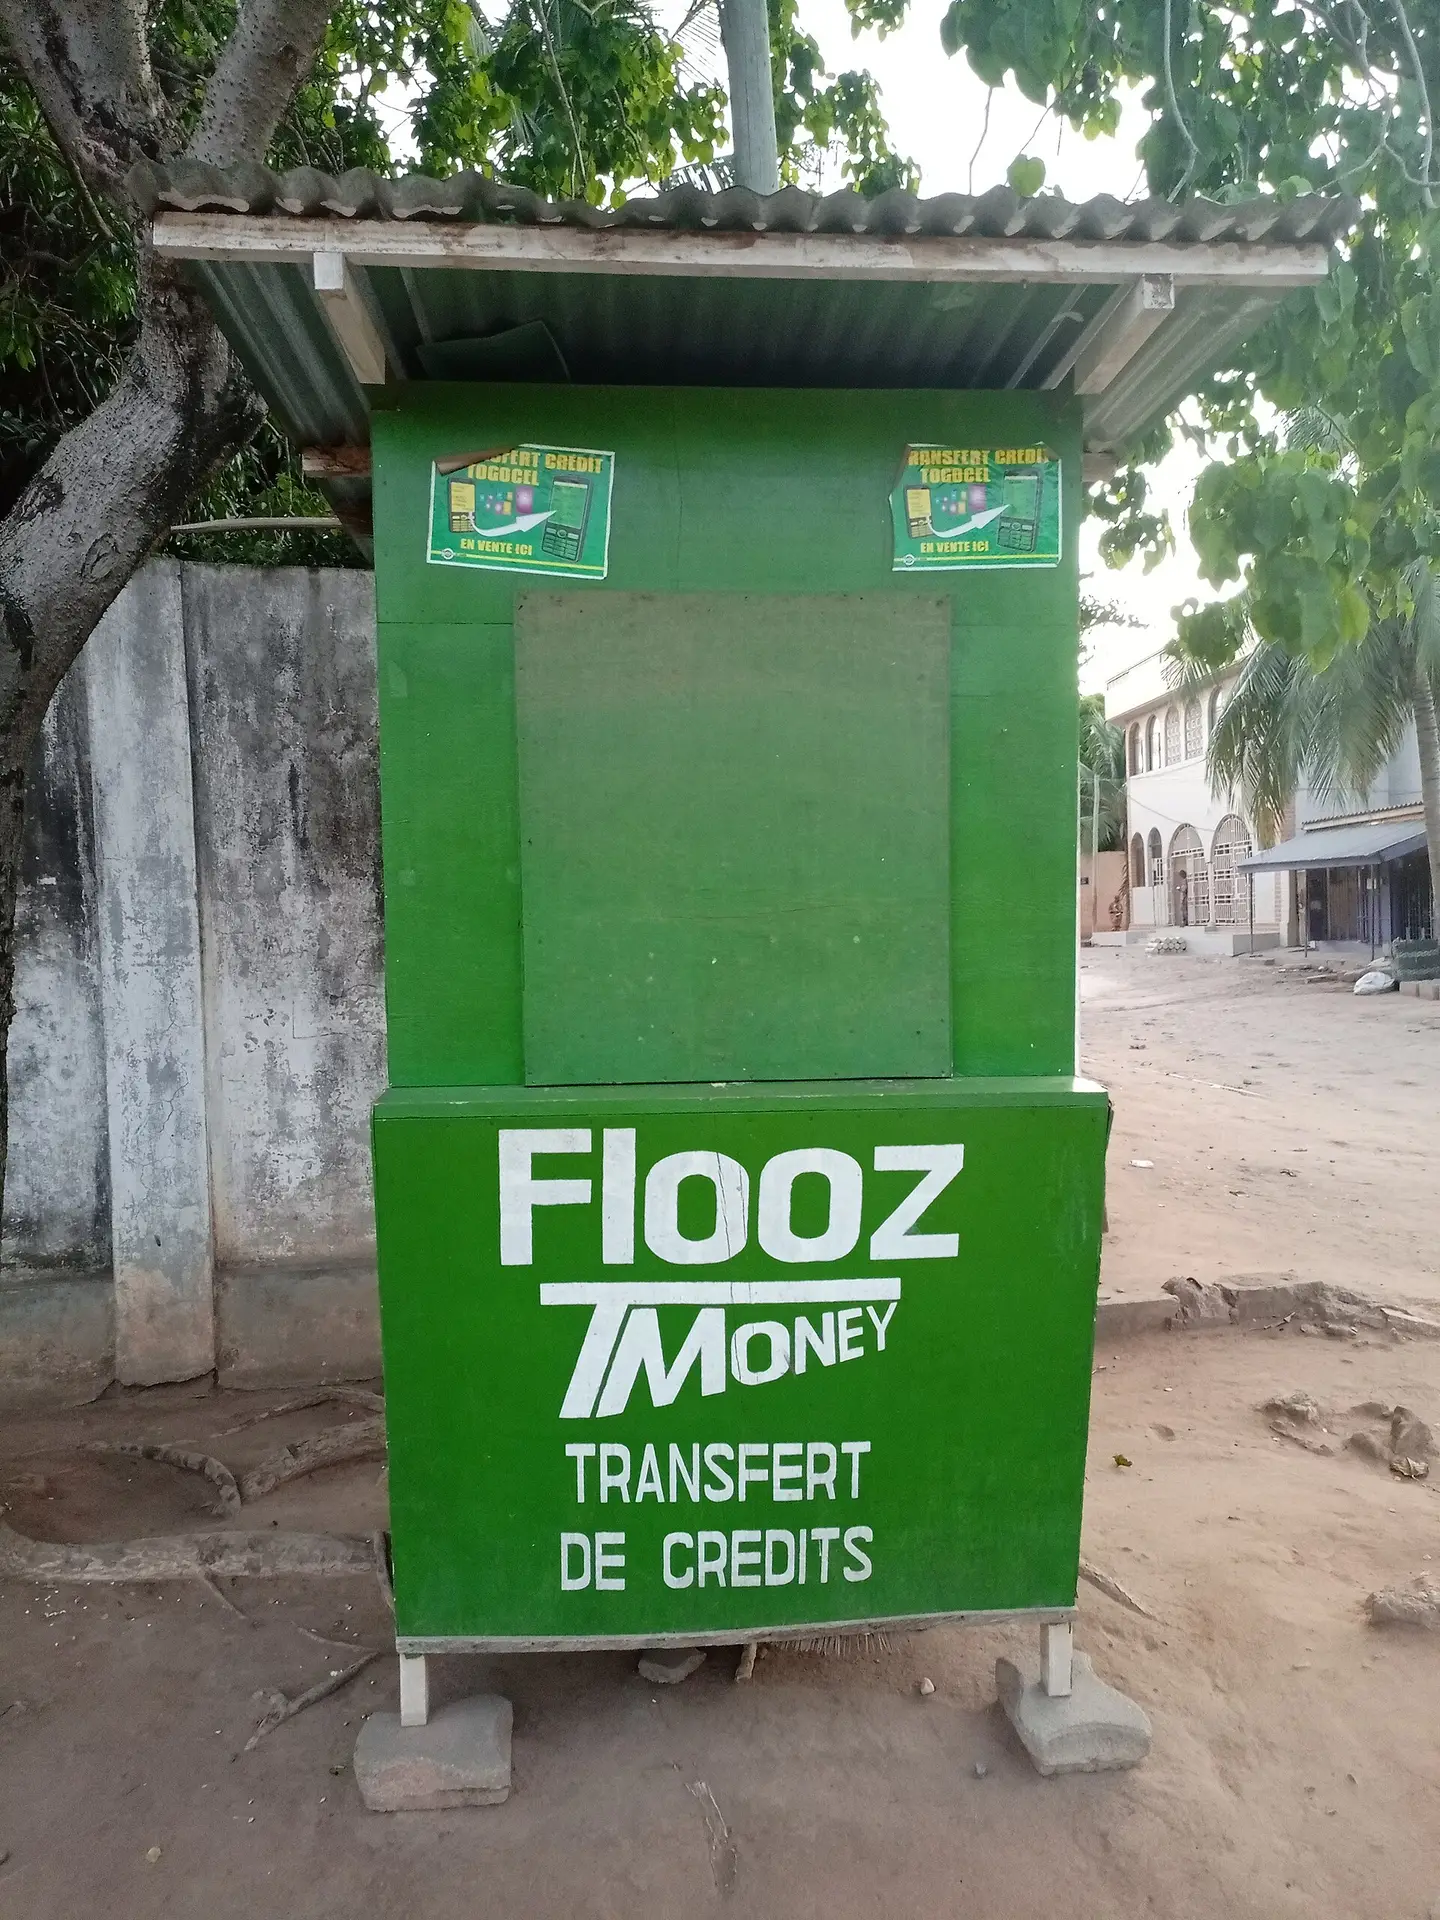
Some corridors already beat the average. Western Africa averages 4.9%, the lowest of any African subregion, according to the IFAD figures in the Capital Ethiopia report. Southern Africa sits at 10.4%, the highest. The same report shows fully digital services averaging 4.59%, against 7.30% for cash-based services.
However, only 35% of the services IFAD measured in 2025 were fully digital at both the sending and receiving ends, IFAD says. Cash still rules many routes. So a cheaper option exists, yet many families cannot reach it. We broke down what a $200 send costs on each route in our remittance cost ladder.
The stakes reach well past one corridor. IFAD counts $728.6 billion sent to low- and middle-income countries in 2025, more than four times global official development assistance. In our view, a fee on private family money deserves the same attention as aid.
What to do if you send money home
For globally minded professionals in London or Atlanta, a monthly transfer home is a budget line like any other. You can negotiate it. Take a sender who transfers $300 a month, or $3,600 a year. At 7.2%, fees cost $259.20. At 3%, they cost $108. The difference is $151.20 a year, and it stays with your family.
- Ask for the total cost in the receiving currency. Exchange rate margins add cost, and a 2024 update on the G20 remittance target notes that Sub-Saharan Africa tends to carry higher margins than other regions.
- Compare two providers before every send, because prices differ by corridor and by provider.
- Choose a fully digital route when your recipient can collect digitally.
- Write down the all-in cost each time. A simple phone note shows you when a provider’s price creeps up.
Who can push remittance fees down
Senders have limited power over remittance fees. Regulators, banks and licensed digital providers hold the levers. We would press for two things. First, every provider should show the total cost, including the exchange rate margin, before the sender confirms. Next, both ends of a corridor should let licensed digital wallets compete, because that is where IFAD finds the lower prices.
Our readers sit on both ends of these corridors. Some send money home while they build careers abroad. Others receive it while they build businesses at home. Both groups share one interest in cheaper rails. Founders who build transparent, low-cost routes serve a market that IFAD sizes at $124.2 billion a year in Africa alone.
The 3% target runs to 2030, which leaves just over four years. Diaspora money already shapes cities from Lagos to Nairobi, as our Detty December budget guide shows. If $5.2 billion stayed with families each year, what would your household build first?
Sources and notes. IFAD press release, 14 September 2026. IPS via AllAfrica, 18 September 2026. Capital Ethiopia, 20 September 2026. United Nations Sustainable Development Goal 10, target 10.c. G20 remittance target update, November 2024. The $5.2 billion, the table and the $151.20 example are TIME AFRICA calculations. This is commentary, not financial advice. All stats are verified and cited.